Restaurants typically draw on three different types of financing depending on the need: equipment financing for kitchen and refrigeration equipment, renovation or buildout financing for dining room and kitchen upgrades, and short-term working capital to smooth out food cost swings and slower stretches. Few restaurants use just one financing product for everything.
Why Restaurant Financing Looks Different
Restaurants combine expensive specialized equipment, thin margins on food cost, and — for most concepts — high daily transaction volume through card sales. That combination of asset-heavy operations and strong daily revenue visibility shapes which financing products tend to fit best.
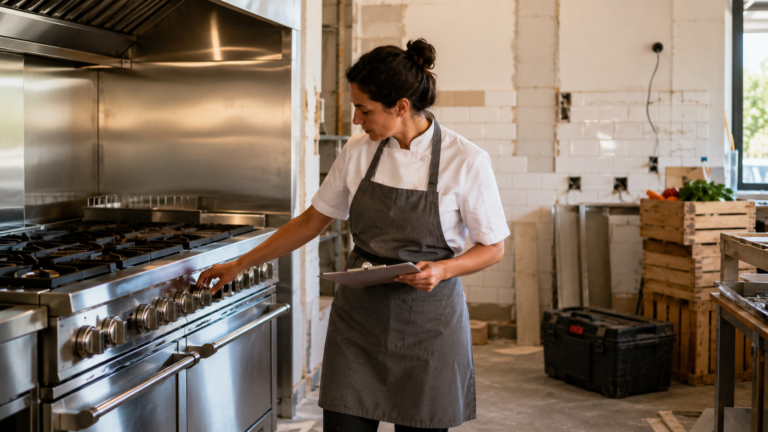
Equipment Financing for Restaurants
- Ovens, ranges, and other core kitchen equipment.
- Refrigeration and walk-in cooler units.
- POS systems and related technology.
- Ventilation hoods and other required kitchen infrastructure.
Financing a Renovation or Buildout
- Dining room remodels and refreshes.
- Kitchen expansions to increase capacity.
- Buildout costs for a new location.
- Permit and compliance-driven upgrades required by local health or building codes.
Working Capital for Food Cost and Slow Stretches
- Covering inventory and food cost swings tied to ingredient pricing.
- Bridging payroll during predictably slower weeks or seasons.
- A Merchant Cash Advance is particularly well suited here, given how directly it ties to daily card sales.
Why Restaurants Often Qualify Well for Revenue-Based Financing
Most restaurants process a high volume of daily card transactions, which gives revenue-based lenders clear, granular visibility into sales performance. That transaction history often makes restaurants a strong fit for products like a Merchant Cash Advance, even when the business’s credit profile alone might not tell the full story.
Frequently Asked Questions
Can I finance a full renovation and new equipment at the same time?
Yes. It’s common to combine equipment financing for the kitchen buildout with a separate renovation loan or working capital product for the dining room and general construction costs.
Does seasonal or slow-season revenue hurt approval for restaurants specifically?
It can factor in, but many lenders account for known seasonal patterns by reviewing a longer window of sales data rather than judging a single slow month on its own.
Why do Merchant Cash Advances work particularly well for restaurants?
Because approval and repayment are both tied to daily card sales, which restaurants generate in high volume — giving lenders strong visibility and giving the restaurant a repayment structure that naturally scales with actual daily performance.
Planning Equipment, a Renovation, or Extra Working Capital?
Apply today and Apex Lending Partners can help you match financing to what your restaurant actually needs right now.